
It's been for a month now ... my dad has been harrowing me with "What's with your stocks ... do property ... it will pay you better". I kinda cant argue with him - given some amazing statistics he's been sharing with me over the last few weeks.
So here's the deal ... please email me some good (and very good) property investments in cities around India from an investment viewpoint (and short term 1.5-2 yrs). Feel free to let me know about residential, commercial, plots etc. But read the billboard again - investments only !!!
Kindly email the same at shankarnath@gmail.com
PS: I like that title ... what say you? Shall I change the blog title to "Liberty. Realty. Equity."
Saturday, February 25, 2006
Liberty. REALTY. Equity.

Bookmark this post: | 


|
NIIT Technologies
Increasing sales, increasing profits, good dividend yield and a P/E lower than industry peers ...
The business stats -
Share capital - 38.65 crs
Loans - 53.90 crs
Investments - 96.97 crs (in grp cos, so cant be factored in NCAV calc)
Net CA - 79.07 crs
FV - 10 rupees per share
Dividend - 5.50 rupees per share
LY profit - 40.25 crs
CMP - 175.00 rupees per share
This calculates to -
Dividend yield of 3.14%
P/E of 16.80
NCAV of 6.51 rupees/share (very low)
The sales and profit growth has been a neat 20% for this FY. I estimate a profit closing of 48 crs for this year and a dividend payout of 5.5 rupees per share (I would not accomodate an increase in dividend as the company is desirous of suitable acquisitions abroad which would be from internal accruals rather than any borrowings - pls note that the cost of funds has increased over the last 2 years in Indian and international markets; also an increase in debt in the balance sheet would affect the credit rating of the organisation and thereby increase the cost of funds).
Given the increase in profits for the year, the P/E moved go down to 14.09 which is much lower than most other software companies.
Infosys Technologies - 41.6
I-flex - 41.7
HCL Technologies - 81.3
Patni Computers - 32.9
Polaris Software - 19.5 (avoid this stock for now)
Satyam Computers - 34.0
TCS - 41.5
Wipro - 51.1
The management of the organisation is excellent and has a good vintage of 25 years. I like the fact that the education arm is present in around 40+ countries around the world including a huge presence in China. (A presence in China with 100+ education centres cannot be bad). This will help leverage the Software solution business in NIIT Technologies.
Disclaimer: My first job was with NIIT Ltd (not NIIT Technologies, I was in the education and training business - it was good fun working with the likes of Sanjeev Shrivastava, Gulraj Bhatia ... and excellent leaders in Mr. Rajender S Pawar and Mr. P Rajendran. This estimate is however devoid of any occupational loyalties. Do the math yourself for comfort.
Bookmark this post: |
|
Friday, February 24, 2006
Rain Calcining and Gujarat NRE Coke
Yesterday, Sonal was rather excited about a tip he received in the morning. His anonymous tipper said "Buy Rain Calcining .. it's about to shoot up". The CMP of the stock was 40.2 in the morning, and before Sonal could check ... he eventually did that at 2:15 pm ... the price of the stock was 48.35 rupees.
In a serious bid to redeem ourselves from this folly, we set out to negate our dissapointment by trying to prove how wrong we would have had been, if we'd bought the stock. So here goes "our search for skewed analysis"
Share capital - 129.00 crs
Loans - 286.07 crs
Investments - 0.00 crs
Net CA - 107.71 crs
FV - 10 rupees per share
Dividend - 0 rupees per share
CMP - 40.2 rupees (morning price)
LY profit - 12.00 crs
At a P/E of 51.12 and an NCAV of negative 13.77 rupees/share, this was sure not practical. However the company has been posting some very good results.
Q1, 2005 : 13.60 crs
Q2, 2005 : 13.05 crs
Assuming similar trends, I estimate a maximum yearly profit of 42 crs because of (a) the tax charges (at a half-yrly income of 26.65 crs, the tax should be around 9 crs; the co. has surprisingly factored -2.51 and +2.71 crs for the two quarters) and (b) the interest charges (apportioned amount for half yr is only 10.91 crs while 10% of 286 crs would be close to 28.6 crs). At 42 crs of profit, P/E comes to 14.89 but the NCAV remains at (13.77). The company might just be in a position to give a dividend of 40 paise, which will not excite any market.
The company is outside my comfort zone. So, we didn't buy the stock. Today it fell to 43.80 rupees on the NSE.
Instead we checked out another company which works in the same industry - Coke/Metallurgical Coke production.
The business stats of Gujarat NRE Coke are -
Share Capital - 94.32 crs
Loans - 52.10 crs
Net CA - 77.15 crs
FV - 10 rupees per share
Dividend - 4.00 rupees per share
CMP - 86 rupees a share (Feb 23)
LY Profit - 90.78 crs
Like Rain Calcining, the profits for Gujarat NRE Coke have grown in Q1 and Q2 - 45.20 (32.76 in Q1, 2004) and 39.01 (27.83 in Q2, 2004). On this basis, I estimate a profit closing for this company at 120 crs for this year, which would mean a P/E of 6.76 (excellent). The NCAV of the stock is 3.36 (low).
Gujarat NRE Coke has one very good feature in it's unutilised debt capacity. On an interest coverage of 4, I estimate a total debt carrying capacity of 226.95 crs on LY numbers. Which means the m-cap of this stock (811.16) is around 358% of it's debt carrying capacity - fairly decent.
Oops.. and did I mention, at a profit of 120 crs - i would estimate a dividend payout of rupees 3.5 (outlay for the company would be 32.92 crs) ... which means a dividend yield of 4.07%.
Confession - I bought this stock yesterday at 89.8 rupees !!!
Bookmark this post: |
|
Monday, February 20, 2006
HCL Infosystems
HCL Infosystems plunged more than 30% today !!!!
The business stats of the stock are enclosed -
Share Capital - 33.44 crs
Loans - 81.31 crs
Investments - 122.77 crs
NCA - 340.60 crs
FV - 2.00 rupees per share
Dividend per share - 6.20 rupees
LY Profit - 132 crs
Thus, we have the following estimates -
1. I estimate the total profit for this FY for HCL Infosystems will be close to 105 crores. At a CMP of 180 rupees (close of day - Feb 20th 2006), that amounts to a P/E of 28.66 (profit may be more, but I'd rather be conservative)
2. Consequently, the dividend yield for this scrip will be at 3.44%
3. From a value perspective, NCAV for the stock is only 22.85 however, please note that this is an IT and ITES company which doesn't hold incredible amounts of NCAs .. barring maybe cash. The cash per share held by the company is however 8.67 rupees per share.
At 180 rupees, HCL Infosystems is rather enticing. The enclosed graph may stun you ... (see at the extreme right) ... for a stock which was comfortably between 240 and 260 for most part of the year.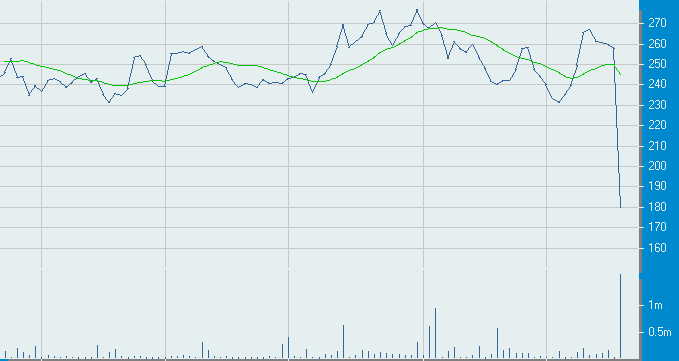
Enclosed are two news stories you may like to read for a better understanding of the events that led up to this bloodbath -
[1] Nokia deal hits HCL Info as brokerages downgrade stock
[2] No reduction in revenues: HCL Infosystems
A very interesting case to analyse and make an investment decision.
Bookmark this post: |
|
Subscribe to:
Posts (Atom)